Retirement is the period in a person’s life when they end their working life and begin living off savings, pensions, or government benefits (such as Social Security). Retirement in the United States is often a carefully planned process aimed at maintaining financial stability and a comfortable lifestyle. It’s a way for people to enjoy themselves and take time for their health, family, and interests after long years of hard work. Typically, the retirement age is between 62 and 67, and it varies based on the rules and individual preferences. A good retirement plan enables people to manage costs, provide income, and live a stress-free, peaceful life after retirement.
What is Retirement Planning and why is it important?
Retirement Planning is a long-term financial planning program to prepare people for retirement. It’s about creating savings, investing, and having a sustainable income in the future. Retirement Planning ultimately aims to provide financial independence in retirement years and to make financial life more comfortable and stress-free. If not given proper Retirement Planning, a person is likely to find himself or herself in monetary uncertainty in his or her old age, thereby lowering the quality of his or her life.
A major factor in the importance of Retirement Planning is that life expectancy is rising, meaning more years in retirement. This calls for increased financial readiness. Retirement Planning is another option that enables people to address inflation, health care costs, and unexpected costs. Early Retirement Planning provides ample opportunity for compound interest to build up savings.
Another significant factor is stability. Retirement Planning helps provide a steady stream of income after retirement. It also empowers individuals to be less reliant on others and more confident about the future. Structured systems, such as Couples Retirement Savings Coordination, are particularly beneficial for couples as they can help coordinate financial objectives and boost savings efficiency.
In sum, Retirement Planning is much more than saving money; it is about creating long-term financial security and peace of mind.
Plan today for a secure tomorrow with smart retirement planning for financial freedom and peace of mind.
Top reasons for retirement planning to achieve long-term financial freedom:
Financial Independence, Stability, and Peace of Mind. One of its best features is the ability to live off passive income without having to devote active income to it. By making early retirement planning decisions, individuals can lay a solid foundation for future financial freedom.
Wealth Growth via Compounding is one of the great benefits of Retirement Planning. Small investments can be highly significant when well managed at the right time. This enables people to save up enough for retirement. A very significant benefit is risk management. Fixed Income vs Common Stock Retirement Planning allows people to achieve a balance between stability and growth. Stocks have a higher return in the long run but are not as safe as fixed income investments. This proportion eliminates financial risk and helps to guarantee consistent growth.
Retirement Planning is also about reducing stress, as it helps to prepare for healthcare and emergencies when you retire. It helps people prepare financially for unexpected events. Couples can do even better when they coordinate their retirement savings through Couples Retirement Savings Coordination, which can help to streamline their savings, eliminate duplication, and consolidate income.
Canadian Physician Retirement Planning offers long-term financial strategies and a retirement plan organized to minimize the impact of taxes on high earners like physicians.
Finally, Retirement Planning results in financial Freedom, so people can enjoy their retirement without worrying about finances.
How much should a couple save monthly for retirement?
The amount of monthly retirement income a couple can enjoy is influenced by their lifestyle, where they live, and how much they spend. As a general rule, couples can sustain their pre-retirement lifestyles with 70% to 80% of their earnings. Here are some factors to consider when determining what a good monthly retirement income is for a couple: Housing, Food, Healthcare, transportation, and Leisure. There is no fixed number of these costs, as they will differ from person to person.
Inflation is a factor that will help determine what a Good Monthly Retirement Income Is for a couple. Retirement income should rise with time, as prices do. The level of health and healthcare costs are also significant determinants of income thresholds.
Retirement Planning is a tool for measuring realistic future income requirements by examining future expenses and savings. Couples Retirement Savings Coordination helps both members save together and more wisely. Most couples have a certain level of income they want and plan to have to live a stress-free life and have all their needs met.
How to determine the appropriate monthly retirement income for a couple.
The first step in determining retirement income is to determine current expenses. This means housing costs (such as rent or mortgage), utilities, groceries, insurance, and health care costs. This serves as the foundation for Retirement Planning. Then, couples have to figure in changes that will happen in the years to come, like fewer work-related expenses and more medical expenses. When calculating inflation, it must also be taken into account.
One of the fundamental approaches of Retirement Planning is to estimate withdrawals. Structured strategies for Fixed Income vs Common Stock Retirement Planning are used by many financial experts to achieve a balance between safety and growth. Couples Retirement Savings Coordination is a key aspect of this process, which involves consolidating both partners’ savings, pensions, and investments into a single plan.
As with any income planning, it is important to focus on sustainability as well as income. With proper calculations, financial security is maintained during retirement. For high-income professionals, additional strategies under Canadian Physician Retirement Planning can be effective, such as optimizing their income structure and tax efficiency. The following are factors that can impact the success of retirement planning.
Plan smart together—calculate your ideal monthly retirement income for a secure and comfortable future.
There are several factors that contribute to a successful Retirement Plan.
Early beginning is the key. The sooner you start saving for retirement, the more time your savings have to grow. Savings discipline is also a big factor, as is income level. Regular investments are more significant than big sporadic ones.
Investment strategy is also a key consideration. A well-rounded retirement plan with a mix of Fixed Income and Common Stock provides a balance between security and growth.
Inflation is a big deal in Retirement Planning as it erodes the buying power over time. Proper adjustments should be made to ensure financial stability. Retirement planning also takes into account health conditions and life expectancy. A longer life expectancy means you need more retirement savings.
Structured Planning Systems, such as Couples Retirement Savings Coordination, can enhance financial alignment and eliminate inefficiencies for couples.
Canadian Physician Retirement Planning is a specialized tax and investment plan for doctors and other medical professionals.
Generally speaking, consistency and discipline are more important factors in Retirement Planning than income. There are some common retirement planning mistakes, and here is how to avoid them.
The number one error in Retirement Planning is to begin too late. Planning that is done late can lead to less compounding and more financial burden later.
Another common error is failing to account for all costs. Many people neglect their healthcare and fail to save enough money due to inflation.
Retirement Planning outcomes are also impacted by bad investments. It is risky not to have any other savings account or to take too much risk without balancing. Fixed Income vs. Common Stock: Retirement Planning.
Investment diversification can help avoid this issue.
People are not always able to coordinate their finances well with the person they are married to. If there is no Couples Retirement Savings Coordination, savings could be sub-optimal or imbalanced.
The second error is withdrawing funds prematurely, thereby diminishing long-term income stability.
The strategies for planning a physician’s retirement can be specialized and, when ignored by those with high incomes, can reduce tax efficiency and optimal returns. These pitfalls can be prevented with proper planning, discipline, and periodic financial checkups.
Planning for retirement at varying ages. Retirement planning for various age groups. Retirement planning in early adulthood should concentrate on saving early and investing in growth assets. The longer the investment horizon, the higher the risk-taking is at this stage.
Retirement Planning is now more formal in the middle years. Consumers save and cut down on unnecessary spending.
At this stage, couples should consider Couples Retirement Savings Coordination to coordinate goals and be more efficient.
Later on, the emphasis shifts to wealth protection. Fixed Income vs Common Stock Retirement Planning is the right way to strike that balance between safety and growth.
Retirement years are the time when the type of income that matters most is retirement income rather than accumulation.
Specialists in their respective professions may use Canadian Physician Retirement Planning to fine-tune their income and tax planning.
The steps you take to prepare for retirement at each stage of life are different, but they all have to stick to one consistent plan.
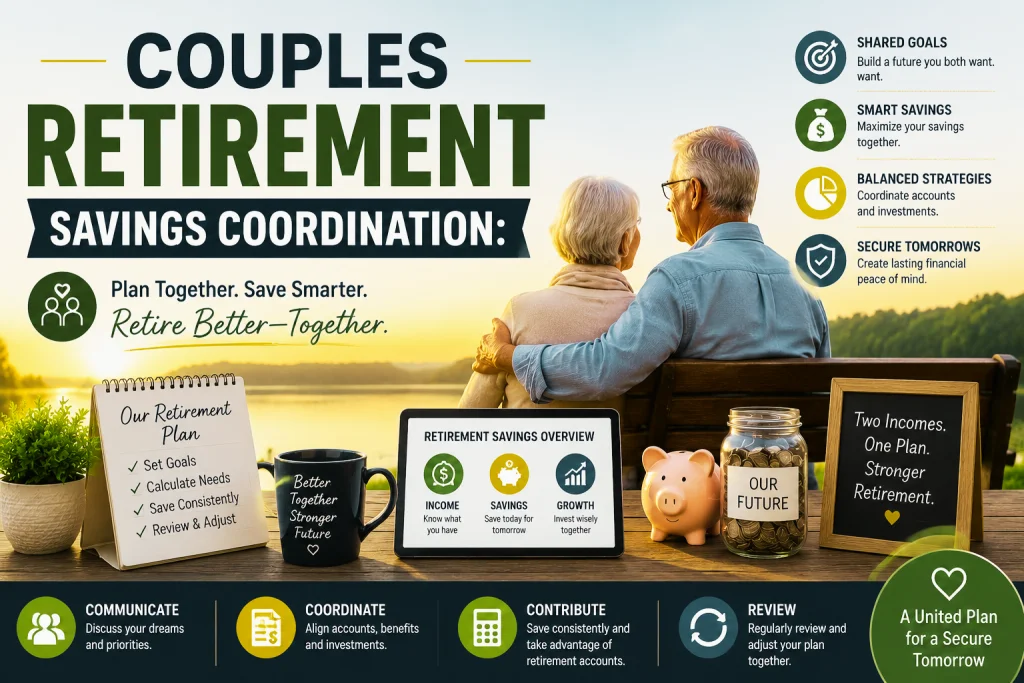
Couples Retirement Savings Coordination:
A Complete Guide is a guide to planning your retirement savings together. Couples Retirement Savings Coordination is an organized approach to helping couples align their financial plans. It emphasizes the need for coordination among income, savings, and investment choices and strategies to achieve common retirement objectives. In the absence of proper Couples Retirement Savings Coordination, couples may experience several inefficiencies, including unequal contributions, duplicate investments, or differing priorities when saving for retirement. The key to having a great Couples Retirement Savings Coordination plan is open communication. It is important for both parties to be aware of each other’s income, liabilities, and financial obligations. Transparency facilitates the building of trust and decision-making together and not alone. This is a key pillar of long-term financial planning. run.
Another important aspect of Couples Retirement Savings Coordination is goal setting. It is important for couples to have a clear idea of what their retirement lifestyle will look like, including the associated travel, healthcare, and monthly expenses. These objectives directly impact savings goals and investment plans.
Another advantage of Couples Retirement Savings Coordination is tax efficiency. When two people get married, their relationship can provide an opportunity to optimize investments and minimize taxes, while also boosting the long-term profitability of their assets. This will enhance the average retirement readiness.
In the end, Couples Retirement Savings Coordination will help provide financial synchronization and minimize potential conflict over retirement planning.
Stronger together—build a smart retirement savings plan that supports shared financial goals and lifelong security.
Best Couples Retirement Savings Coordination Strategies:
Three key strategies for couples to coordinate their retirement savings. Here are a few effective techniques you can use to improve long-term financial results and to enhance couples’ retirement savings coordination. An effective approach is joint budgeting, sharing income and expenses. This gives an up-to-the-minute view of cash flow and the savings potential.
A key component of Couples Retirement Savings Coordination is maintaining separate investment accounts while sharing retirement goals. This will provide flexibility while also moving toward a common financial objective.
Emergency fund planning is also crucial. One way couples can do this is by establishing a common emergency fund of 6-12 months of expenses. This further enhances financial stability and helps to alleviate stress during unexpected situations.
Diversification is an important factor in couples’ coordination of their retirement savings. It’s important for couples to diversify their investments and not put all their savings into a single category, such as stocks, bonds, or real estate.
Communication is still the most crucial strategy. Regular financial conversations keep couples’ retirement savings coordination on track as goals and life situations evolve. People in a relationship can use these tips to build a healthy financial foundation and secure a future for retirement.
The key differences between Fixed Income and Common Stock
Retirement planning is explained. Explanation of key differences between Fixed Income and Common Stock Retirement Planning. One of the most important principles in creating a well-balanced retirement portfolio is Fixed Income vs Common Stock Retirement Planning. Fixed-income investments include bonds, savings accounts, and government securities, offering predictable, stable returns. Common stocks are ownership shares in companies and have the potential for higher growth, but greater risk.
The primary difference between Fixed Income vs Common Stock Retirement Planning is the risk and reward. Fixed income is less risky and more applicable in the later stages of life, where capital preservation is the key objective. But stocks are more appropriate for long-term investing in the early and middle years of a career.
The other distinction concerns income stability. Fixed income pays a fixed amount of interest periodically, whereas equity pays dividends and appreciation. This is why it’s crucial to have a Fixed Income vs Common Stock Retirement Plan in place to achieve a balance of stability and growth.
The level of market volatility also influences investment types in different ways. There is more volatility in stocks and relative stability in fixed income in down markets.
In the long run, it is important to maintain a balance between the Fixed Income and Common Stock Retirement Plans. Having both types of assets can be the best way to minimize risk and maximize growth over time.
Selecting a fixed income or a common stock retirement plan. Deciding on fixed income versus common stock retirement planning.
The ratio of Fixed Income to Common Stock in Retirement Planning is based on age, risk tolerance, and financial objectives. The younger generation is more interested in stocks, as they have time to offset market fluctuations. Elderly individuals tend to prefer fixed-income bonds because they can be safe and offer predictable returns.
One of the key factors in the Fixed Income vs Common Stock Retirement Planning decision is risk tolerance. A conservative investor seeks stability, whereas an aggressive investor seeks higher returns.
Then too, income requirements play a role in decision-making. Fixed income assets are important to retirees who need to receive fixed monthly payments. Growth-oriented investors depend more on stocks.
Diversification is an essential key in Fixed Income vs Common Stock Retirement Planning. A balanced portfolio helps minimize risk and sustain long-term performance.
The ideal combination will ultimately rely on an individual’s retirement objectives and financial situation.
Everything you need to know about Canadian Physician Retirement Planning.
Canadian Physician Retirement Planning is a specific financial strategy for Canadian physicians. Doctors tend to earn a lot of money but may face different career obstacles, including late-career entry, complex tax codes, and a busy work schedule.
Effective Canadian Physician Retirement Planning involves accumulating wealth over time while minimizing tax payments. Physicians use professional corporations and tax-advantaged accounts to maximize their savings.
Diversification is an integral part of Canadian Physician Retirement Planning. Doctors typically mix equities, fixed income, and real estate to achieve a balance of growth and stability.
There’s another key point related to income timing. It’s typical for many physicians to start saving for retirement later than other professionals, so disciplined Canadian Physician Retirement Planning is vital to getting a head start on retirement goals. Estate planning is also a key aspect. A well-structured estate plan can facilitate the transfer of wealth and financial security to family members. Physicians can become financially independent even after retiring from their medical practice with proper planning.
Tax-Efficient Canadian Physician Retirement Planning Strategies.
One of the most crucial factors in Canadian Physician Retirement Planning is tax efficiency. The medical profession frequently forms professional corporations, which enable them to spread taxes out more effectively and to invest retained earnings.
Income splitting is one of the important strategies that can lower the tax burden and enhance the efficiency of savings. Another approach to Canadian Physician Retirement Planning is to contribute as much as possible to tax-sheltered accounts.
The diversification of investments is also a significant factor. Many doctors opt to mix growth and income investments to guarantee stable long-term returns.
Another important aspect is insurance planning. It safeguards the financial well-being and security of dependents.
With changes in tax laws and income over time, regular financial reviews help optimize Canadian Physician Retirement Planning strategies.
Creating a well-balanced retirement portfolio.
By diversifying your portfolio, you will be more likely to succeed in the long run. It Diversify smartly, invest wisely, and build a strong retirement portfolio for long-term financial stability. Retirement Compensation Arrangement Explained: Ultimate Powerful Benefits, RCA & SERP Guide 2026onsists of a variety of stocks, bonds, real estate, and savings options. Diversification helps to minimize risk and maximize return.
A strong portfolio strikes a balance between growth and stability. This is where the concept of Fixed Income vs Common Stock Retirement Planning becomes critical in ensuring proper asset allocation.
There is a need to make changes to a retirement plan based on age and risk tolerance. Younger people are more concerned about growth-oriented assets, and the elderly are more concerned about income stability.
Diversification is also a way to shield from market volatility and economic uncertainty. Couples Retirement Savings Coordination is an excellent way for couples to coordinate their retirement savings goals in their portfolios. A wide range of approaches ensures long-term sustainability and financial security.
This is a final retirement planning checklist for professionals and couples.
Retirement Planning needs to be evaluated and adhered to regularly to make a strong plan. The first step is to practice regular, conscious saving and investing. Regular monitoring facilitates financial discipline.
To have realistic retirement plans, it’s important to understand the average monthly retirement income for a couple. It is important to calculate the amount of income needed for a comfortable living.
Fixed Income vs Common Stock Retirement Planning provides balance with stability and growth.
To prevent conflict and inefficiencies, couples should ensure they are well aligned financially and coordinate their retirement savings through Couples Retirement Savings Coordination.
Canadian Physician Retirement Planning is designed to maximize tax efficiency and structuring of wealth over time for professionals, especially doctors.
A healthy retirement plan is rounded out with periodic financial checks, diversification, and risk management.
Frequently asked questions (FAQs).
1.In the USA, at what age does one receive Social Security benefits?
In the USA, a person is eligible to retire at full retirement age – that is, 67 years for most – but not all.
Early retirement can be taken at the age of 62.
Reduced monthly retirement benefits are provided for early retirement.
The longer you delay your retirement, the higher the payment will be.
Lifetime income varies according to age choice.
2. What is the beginning of the retirement process in the USA?
There is an online application on SSA.gov.
Alternatively, you can apply by phone or in person.
Select the starting time for retirement.
Provide information and paperwork as needed.
Funds are paid upon approval.
3: What documents do you have to use to apply for a retirement benefit in the USA?
Your Social Security Number will be required.
Must have a birth certificate.
Valid Identification (ID) – such as a passport or driver’s license.
Resumes and/or tax records.
The bank information to deposit payment.
4. What’s the Social Security benefit I’ll get once I retire?
It’s based on working income.
The higher your earnings go, the higher your benefits will go.
Lower payment due to early retirement.
The longer you wait, the more income you’ll have every month.
Exact estimates are available online from SSA.
5. Are there any retirement benefits for foreign nationals in the USA?
Yes, if they are doing something in the USA.
Minimum of work credits must be achieved.
Some countries have an agreement.
Benefits can be paid overseas.
Rules vary by case.
6. What is the age difference between early retirement and full retirement?
You can begin the early retirement phase at age 62.
Retirement is at 67 (66 for people born before 1964).
Early translates to fewer benefits.
7.What you see is what you get with full age.
Higher benefits to wait.
Social Security retirement benefits are computed using a formula. The computation of Social Security retirement benefits is based on a formula.
The same applies to the value of low years, which are considered zero.
Inflation-adjusted earnings are used.
The last amount is determined by a formula.
The more one earns, the more benefits he or she receives.
8. Do I qualify for benefits if I start my retirement before turning 65 when I’m working in the USA?
Yes, you can still work, but it requires extra time.
There are restrictions up to full age.
Additional income could lead to reduced benefits.
There is no penalty after full age.
Many retired individuals have small jobs.
9. What are the impacts of taxes on retirement income in the U.S.?
Part of the Social Security benefits could be taxable income.
Depends on the level of total income.
As high as 85% can be taxed.
Other states also levy income taxes.
Tax planning decreases taxes.
10. How to access the status of my SS retirement payments online?
Please use the official SSA.gov website.
Create a “My Social Security” account.
Log in securely anytime.
Conclusion
Retirement is a vital period in an individual’s life, closely linked to financial planning, Social Security benefits, and long-term stability in the United States. With an understanding of the most important questions in Parts 1 and 2, it’s easy to see that retirement is not merely about leaving the workplace – it’s about beginning a new chapter of life that is both financially secure and independent, while also bringing peace of mind. With proper planning before retirement, people can enjoy the rest of their lives without being burdened with financial issues, and Social Security is a big factor in helping millions of retired Americans each month.
The retirement age in the USA is one of the most crucial arguments that is discussed. The retirement age can range from 66 to 67, depending on year of birth, and can start at 62. This flexibility enables the person to retire when they wish, based on their individual financial circumstances, health, and lifestyle goals. This decision, however, directly affects monthly benefits. People who opt for early retirement will get less money, while those planning to retire at age 70 will get more money each month. This system promotes people to work longer if they can, thus enhancing their financial situation in the long run.
One important factor is how people begin the retirement process. Today, with technology, it has become much easier via the Social Security Administration (SSA) website. Applicants can submit their applications online, by phone, or in person at a branch. Requires direct deposit banking information, work history, and personal identification. Monthly payments start once approved and are based on the chosen retirement date. This system makes millions of Americans eligible to receive retirement benefits in a transparent, efficient manner.
Documents play a significant role in the retirement application process. A Social Security Number, birth certificate, government-issued ID, and work-related tax records are essential documents to check eligibility. The documents ensure that the applicant is able to receive benefits and has a valid work history. Sometimes other papers, such as marriage records, military service records, etc., will also be required. Having the right documentation helps process benefits and prevent delays.
An important distinction is also that between early retirement and full retirement age. Early retirement gives you benefits at reduced amounts; full retirement age gives you benefits. Payments can be further increased if retirement is delayed until age 70. Such a system should provide flexibility, but decision-making is necessary. Individuals have to find a compromise between their needs and long-term income security.
The second major one is the formula used to determine Social Security benefit rates. Average indexed monthly earnings (based on the highest 35 years of earnings). If there are lower or missing earnings years, they count as zero and may reduce the final benefit amount. This formula is designed so that all account holders are treated fairly, irrespective of how long they’ve been with the bank. Adjustments for inflation also help to preserve the value of benefits over time.
Overall, US retirement planning is a well-organized, structured process that prioritizes financial security and long-term well-being. Many people rely on Social Security benefits as their source of income in retirement. But the amount and success of retirement income are largely reliant on planning, consistent income, and decision-making. The choices of early, full, and delayed retirement each have pros and cons.
Explaining the rules, benefits, and how to figure them out enables individuals to make better financial decisions. Retirement should be looked upon not as the end of working days but rather as a new chapter that brings financial independence and peace of mind. If you know what you need to do and plan accordingly, you can secure a safe and comfortable retirement in the U.S. for yourself and your family.
Welcome to USA Senior Citizen, a trusted resource dedicated to helping older adults live healthier, happier, and more independent lives.
Our mission is to provide valuable information, practical tips, and helpful guidance for seniors and their families. We cover important topics including **senior health, retirement planning, senior living, caregiving, technology for seniors, and everyday lifestyle solutions**.
At USA Senior Citizen, we believe aging is not about slowing down — it is about embracing new opportunities, staying connected, and enjoying every stage of life. Our goal is to make life easier for seniors by sharing simple, reliable, and easy-to-understand information that supports better decisions and improved well-being.
Whether you are looking for advice on maintaining a healthy lifestyle, exploring retirement options, learning new technology skills, or finding ways to stay active and independent, USA Senior Citizen is here to guide you.
We are committed to creating a supportive online community where seniors can discover useful resources, gain confidence, and continue living life with dignity and purpose.
USA Senior Citizen — Empowering Seniors to Live Better Every Day.